Is a smaller home the right move for you? Let's look at real homes and real numbers. Then you can decide with clarity.
Every downsizing decision is personal. For some, it's a choice. For others, the house has started to make the choice for them. Either way, it's your call. Every situation is different.
You're comfortable where you are. A smaller home sounds appealing, but the numbers matter. You'll weigh:
Staying put can be a smart choice too.
Finances may play a larger part in the decision.
Perhaps:
Here, ease and comfort often come first. A home that works for you every day is worth a great deal.
Daily life may play a larger part in the decision.
Many people expect a smaller home to cost far less. Often it doesn't. A single-level home usually costs more per square foot than a two-story home.
It needs a larger foundation and roof for the same living space. So the equity you free up may be smaller than you expect.
That's why we start with real homes and real prices.
I'll prepare:
Just clear numbers.
Request My ComparisonFor many homeowners, the house is their largest asset. Downsizing can turn some of that value into choices. You might travel, invest, help family, or simply keep a comfortable cushion.
How you use it is entirely up to you.
Two questions shape how much you keep: capital gains, and today's mortgage rates.
When you sell your main home, federal tax law lets you exclude part of your profit from tax:
To qualify, you generally must have owned and lived in the home for at least two of the last five years.
It's your gain, not your equity, that counts. Your gain is roughly your sale price, minus selling costs, minus what you paid and the improvements you've made over the years. Many owners have more room under the limit than they think.
A married couple filing jointly would owe no federal tax on it. A single filer would have about $220,000 above the limit.
Keep your receipts. Records of past remodels, additions and major upgrades can lower your taxable gain.
These limits were set in 1997 and have never been adjusted for inflation. Congress is considering bills to raise them. As of October 2026, none has become law.
I'm a Realtor®, not a tax advisor. Please confirm your numbers with a CPA before you decide. Source: IRS Topic 701 ↗, reviewed September 2026.
Many homeowners have a mortgage rate between 2.5% and 3.5%. Today's rates are above 7%. Trading one for the other is a hard pill to swallow.
But your payment depends on how much you borrow, not just the rate.
Using your equity to borrow less can keep your payment close to what it is today.
7.28% was Freddie Mac's average 30-year fixed rate for the week of October 1, 2026. Illustration only. Taxes, insurance and HOA dues are not included.
Ask me for a lender. They can run your real numbers before you commit to anything.
If you love your home but it no longer fits daily life, adapting it may be the better move. Adding a main-floor bedroom and bath, or simplifying a yard, can make a home work for years to come.
I can introduce you to contractors for quotes. The right answer is the one that fits your life.
Timing is often the biggest worry. Here are your main options.
We'll choose the right path together, with a lender's input.
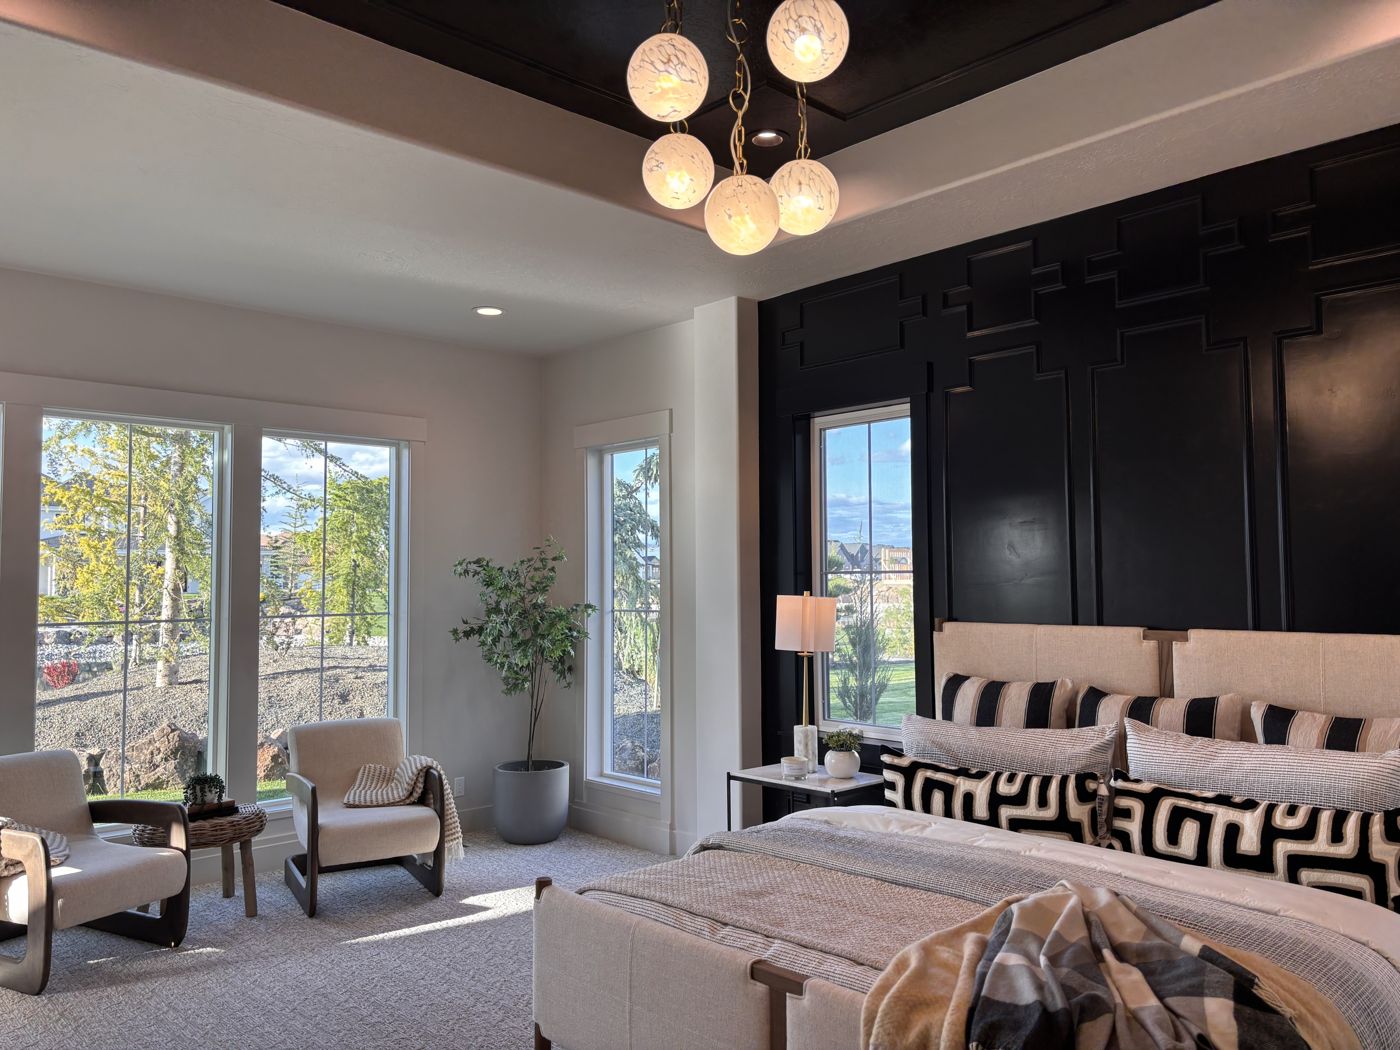
Everything on one floor.
See Homes →Smaller lots, often with HOA-maintained yards.
See Homes →Modern layouts, builder warranties, sometimes rate incentives.
See Homes →Lock-and-leave living, including downtown Boise.
See Homes →Age-restricted neighborhoods, often with a clubhouse and fitness center. Rules vary by community.
See Homes →
If you're selling in a higher-priced market, your equity may go further here. Many of my clients sell one home out of state and buy here in a single, coordinated plan.
One plan for both sides of your move, so you always know what comes next.
Your goals and your Downsizing Comparison.
Home prep, repairs and staging.
Marketing, negotiation and coordinated timing.
Closing, keys and trusted local contacts.
It depends on your equity, your loan options and your timeline. A short call with me and a lender will show which path fits.
Many sellers won't. The exclusion is up to $250,000 single or $500,000 married, and it applies to your gain, not your equity. Confirm with a CPA.
Not always. Single-level homes often cost more per square foot. That's why we compare real prices first.
Often, yes. A short rent-back can be part of your sale agreement.
No. Apply with your county assessor for the new home. The exemption can remove up to half your home's value, to a maximum of $125,000, from property tax. Source: Idaho State Tax Commission ↗.
This page is general information, not legal, tax or lending advice. Figures are illustrations; your numbers will differ.
Request your Downsizing Comparison. No obligation, just clear numbers.
Get the Treasure Valley market update each month, plus my newsletter with new articles and guides. Unsubscribe anytime.