You may need far less than you think.
Many renters believe they'll never save enough for a down payment. In Idaho, that's often not true.
Two paths to your first home.
Between state assistance, low-down-payment loans and help with closing costs, many buyers get into a home with far less of their own money than they expect. And if you're a few years away, Idaho rewards you for saving.
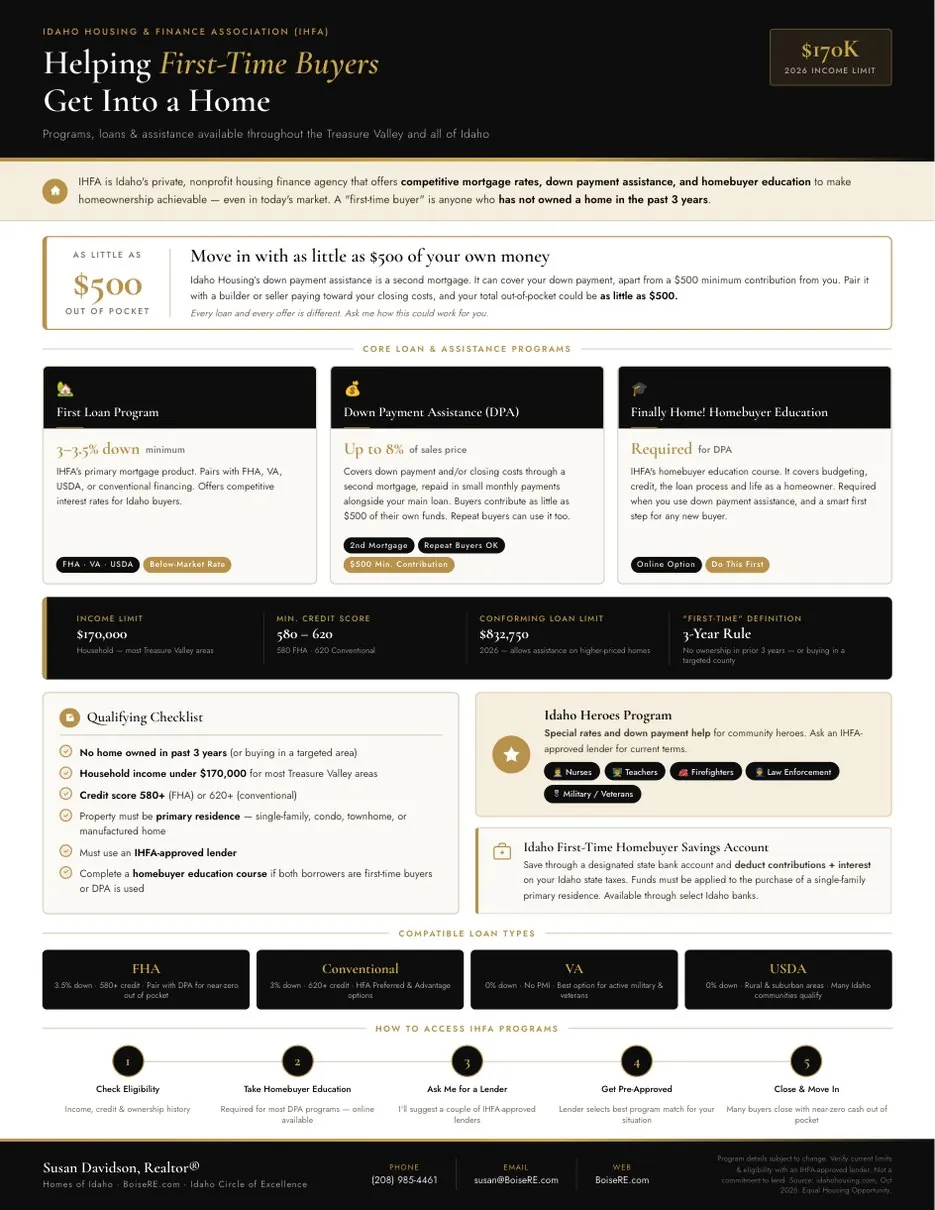
Get into a home with as little as $500 of your own money.
The math that surprises people
Example: a $400,000 home with a conventional loan
A few costs, like your home inspection, are paid before closing. I'll walk you through every one.
Programs that make it possible.
Idaho Housing down payment assistance
- Up to 8% of the sales price toward your down payment and closing costs
- A second mortgage, repaid in small monthly payments alongside your main loan
- You contribute as little as $500 of your own money
- Household income at or below $170,000 in most Treasure Valley areas
- Repeat buyers can use it too
Low-down-payment loans
- FHA: 3.5% down, 580+ credit
- Conventional: 3% down, 620+ credit
- VA and USDA: 0% down for those who qualify
Bank and credit union programs
Many local lenders have their own first-time buyer programs. Idaho Central Credit Union (ICCU) is one example. It offers a 100%-financed first-time buyer loan and a 40-year loan with lower monthly payments, each with a $1,000 minimum contribution.
Check with your own bank or credit union, or ask me for a couple of recommendations.
Who pays the closing costs?
- New constructionBuilders often offer incentives, such as paying closing costs or buying down your rate, to keep sales moving.
- Resale homesIn a slower market, some sellers will pay toward your closing costs rather than lower their price. In a hot market, sellers have little reason to offer this.
- Loan limitsLoan rules cap how much a seller can contribute. FHA loans, for example, allow up to 6% of the price.
I'll tell you honestly what's realistic in today's market.
Four steps to your first front door.
- 1Take the Finally Home! courseIdaho Housing's online homebuyer class. Sign up
- 2Ask me for a lender recommendationI'll share a couple of trusted lenders so you can choose the best fit. Ask Susan
- 3Get pre-approvedYou'll know your real budget, and your offer will be stronger.
- 4Start touringI'll help you find the right home within your approved range.
Start saving now, with a tax break.
Most people have never heard of it. The Idaho First-Time Homebuyer Savings Account lets you deduct what you save for your first home from your Idaho income taxes. If buying is a few years away, this is the time to start.
if single
if married filing jointly
on deposits
How it works
- Open the account at an Idaho bank or credit union.
- Your deposits and the interest they earn are deductible on your Idaho return.
- Withdrawals for your down payment and closing costs are tax-free.
- Withdrawals for anything else are taxed.
- No withdrawals in the first 30 days after opening.
Who it's for
- Idaho residents who file an Idaho income tax return.
- People who have never owned a home.
Note: Idaho Housing's down payment assistance uses a different rule, "not owned a home in the past 3 years," and repeat buyers can use it too.
Talk with your tax professional about your own situation. I'm a Realtor®, not a tax advisor.
Keep reading, or pass it on.
Know someone who thinks they can never buy? Share this page or the one-page guide with them.
First-time buyer questions.
Is down payment assistance free money?
No. Idaho Housing's down payment assistance is a second loan that you repay over time in small monthly payments. It means you don't have to save the full amount upfront.
Do I have to be a first-time buyer?
Not for Idaho Housing's down payment assistance. Repeat buyers can use it too. The Idaho First-Time Homebuyer Savings Account is different: it is for people who have never owned a home.
Can I combine programs?
Often, yes. For example, you can pair Idaho Housing assistance with a builder or seller paying toward your closing costs. Your lender confirms which programs work together.
What is the Idaho First-Time Homebuyer Savings Account?
A savings account at an Idaho bank or credit union. Deposits and interest are deductible on your Idaho income tax return, up to $15,000 a year if single or $30,000 if married filing jointly, with a $100,000 lifetime limit. Withdrawals for your down payment and closing costs are tax-free.
Program details change. Figures checked October 2026 with the Idaho Housing and Finance Association, the Idaho State Tax Commission and ICCU. ICCU is shown as an example only. This page is general information, not lending, legal or tax advice. Equal Housing Opportunity.
Your first home may be closer than you think.
Tell me where you are today. I'll show you what's realistic and who can help.
Stay a step ahead of the market.
Get the Treasure Valley market update each month, plus my newsletter with new articles and guides. Unsubscribe anytime.